
Wastewater infrastructure is moving higher on the private-investment agenda. Cities, utilities and industrial sites need assets that collect, treat, reuse and safely discharge used water. The opportunity is real, but the investable unit is not a broad market headline. It is a defined asset, contract, service or technology with a paying customer and measurable performance.
For private investors, the central question is whether infrastructure spending becomes durable cash flow. That requires more than a treatment plant or a large project pipeline. It requires clear responsibility for payment, credible approvals, delivery evidence, operating resilience and a funding model that can support the asset through its full life.
This outlook explains where wastewater infrastructure creates commercial demand across the UK, Europe and the Gulf Cooperation Council (GCC). It is educational content, not regulated financial advice. It does not promise returns or recommend a particular investment.
Wastewater infrastructure: investment thesis at a glance
| Question | What to test |
|---|---|
| Demand driver | Is the spend linked to capacity, compliance, resilience, reuse or an industrial operating need? |
| Paying customer | Which utility, municipality, industrial site, developer or offtaker is responsible for payment? |
| Revenue model | Does cash flow come from construction, equipment, operations, availability, treatment volume, data or a blended structure? |
| Scalability | Can delivery repeat through a standard design, service network, platform or asset programme? |
| Principal risks | What could delay permitting, construction, commissioning, utilisation, payment or renewal? |
| Impact evidence | Can the business measure treatment performance, avoided discharge, reuse or improved resilience? |
The thesis is strongest when a defined need has a defined budget and a defined route to delivery. A large addressable market is useful context, but it does not replace evidence that the asset can be built, operated and paid for.
What wastewater infrastructure includes
Physical assets across a connected system
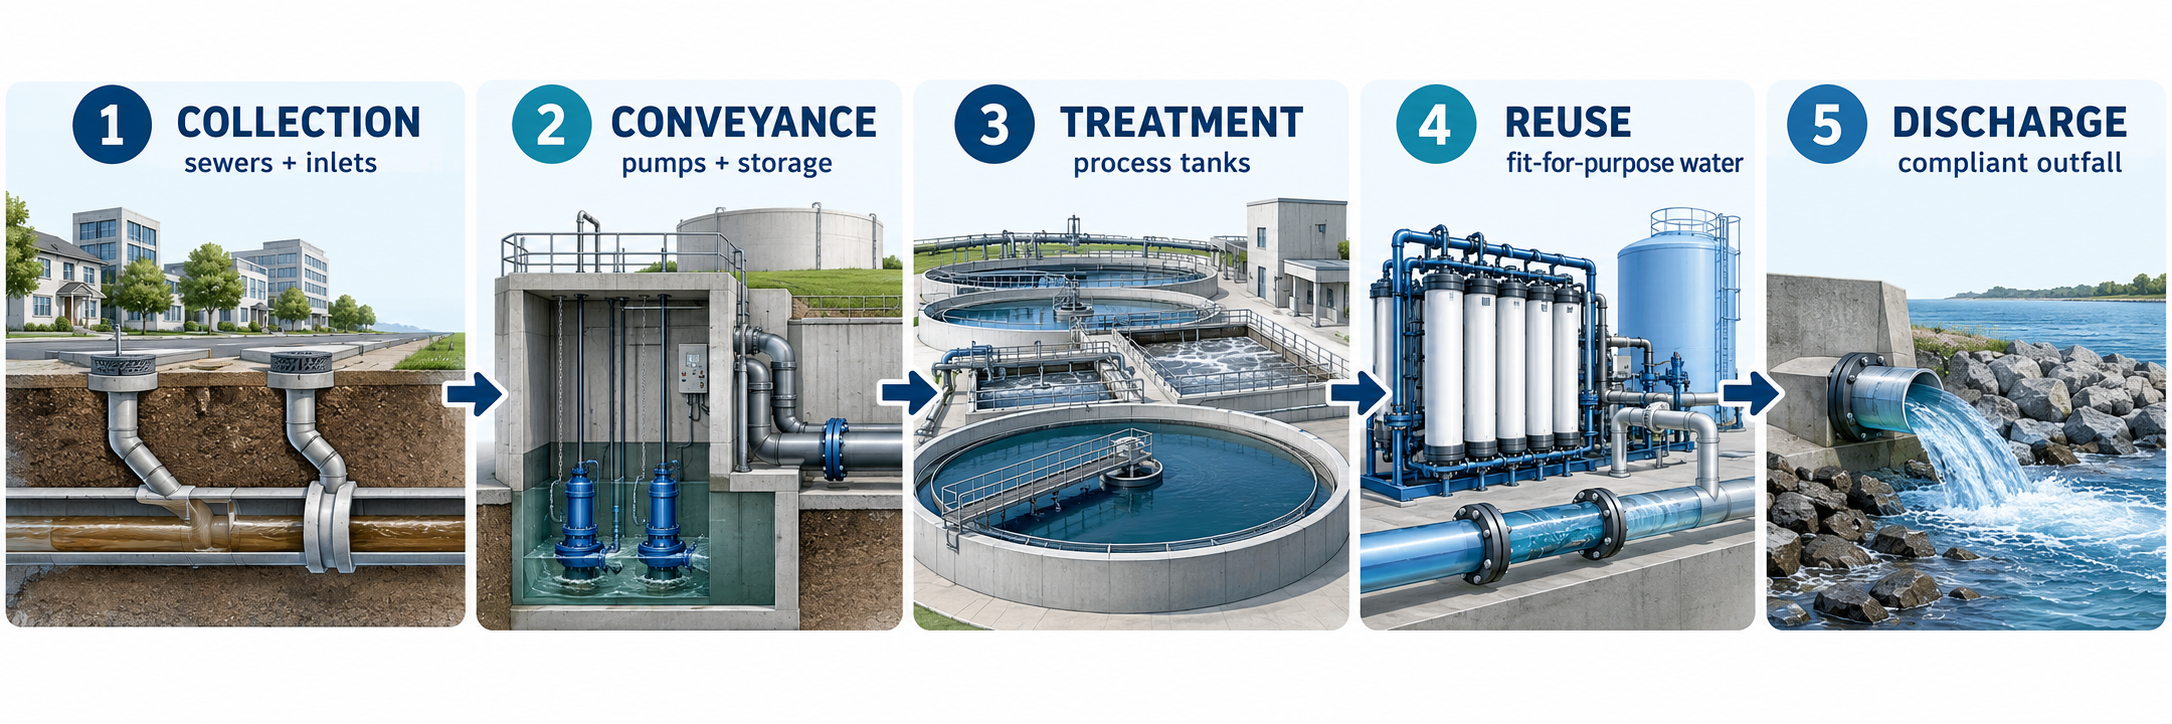
Wastewater infrastructure includes collection networks, pumping stations, storage, treatment works, outfalls, monitoring equipment, reuse systems and supporting digital controls. The term can also include specialist operators, maintenance platforms and project companies that own or manage these assets.
A collection network moves wastewater to treatment. A treatment works removes pollutants before discharge or prepares water for a specified reuse. Storage and stormwater assets manage peak flows. Reuse infrastructure connects treated water to an industrial, municipal or agricultural customer. Each component has different utilisation, maintenance and regulatory risks.
Asset labels do not define the risk
Two treatment plants can have very different economics. One may serve a stable utility catchment. Another may depend on a single industrial customer and a long-term offtake agreement. One network may have regulated funding. Another may rely on a developer, municipality or project-finance structure.
Investors should map the asset to its owner, operator, customer, permit, contract and capital provider. This prevents a broad wastewater sector narrative from hiding the actual source of revenue and the party carrying performance risk.
Why wastewater infrastructure demand is becoming more visible and who pays
Ageing assets meet higher operating requirements
The European Investment Bank says European water systems face pressure from climate change, biodiversity loss, ageing infrastructure and growing water needs. Its 2026 paper also says the challenge is how investments are originated, coordinated, funded and financed. For investors, that points to a project-formation problem as well as an asset-renewal problem.
In the UK, drainage and wastewater management plans look at current and future network capacity, climate change, population growth and other risks over at least 25 years. This long planning horizon supports visibility, but it does not guarantee that every planned scheme reaches procurement or construction.
Regulation creates work, not automatic profit
The European Commission’s water resilience strategy identifies public and private investment, infrastructure modernisation, digitalisation and innovation as areas of action. It also links water resilience to the wider economy. The practical investment signal is a policy direction and pipeline of potential work, not a guaranteed margin for suppliers.
Regulation can strengthen demand because a utility or industrial operator must meet a requirement. It can also increase price pressure, procurement complexity and delivery scrutiny. An investor should identify the exact obligation, deadline, responsible entity and funding route before treating a regulatory theme as revenue.
Utilities and municipalities
Utilities and municipalities may need network rehabilitation, treatment upgrades, stormwater controls, monitoring and additional capacity. Their purchase decisions can be shaped by asset plans, permits, service standards, tariff settlements, public procurement and political oversight.
For a private company, the commercial opportunity may sit in a long-term service contract, a framework, a design-and-build package or a specialist component. The investor should trace the path from public need to approved scope, contracted work, payment and renewal.
Industrial and real-estate customers
Industrial sites may invest to protect production, meet discharge conditions, reduce freshwater use or expand a facility. Developers may need wastewater capacity before a site can be occupied. These customers can value speed and certainty, but they may demand performance guarantees, integration work and local support.
The most useful commercial test is budget ownership. Identify who controls the spend, what alternative the customer would use, how urgent the decision is and which technical or legal approvals sit between a proposal and a paid deployment.
Reuse and resilience buyers
The World Bank’s Scaling Water Reuse report says the business case is strongest when wastewater is close to the point of use, including urban centres and industrial parks. That proximity can reduce the cost and complexity of moving water, but the project still needs fit-for-purpose treatment, a reliable offtaker and clear rules for quality, liability and pricing.
Resilience spending can also create demand for storage, diversified supply, decentralised treatment and monitoring. The customer may be buying avoided interruption rather than water alone. That value must be translated into a contract, a service level, a capacity payment or another mechanism that can be measured.
How wastewater infrastructure businesses make money
Four common commercial models
Wastewater infrastructure businesses often combine several models. Equipment and construction revenue arrives around delivery. Operations and maintenance revenue recurs through service. Asset or project revenue may depend on availability, treatment volume or capacity. Monitoring and data revenue may support compliance, optimisation or early fault detection.
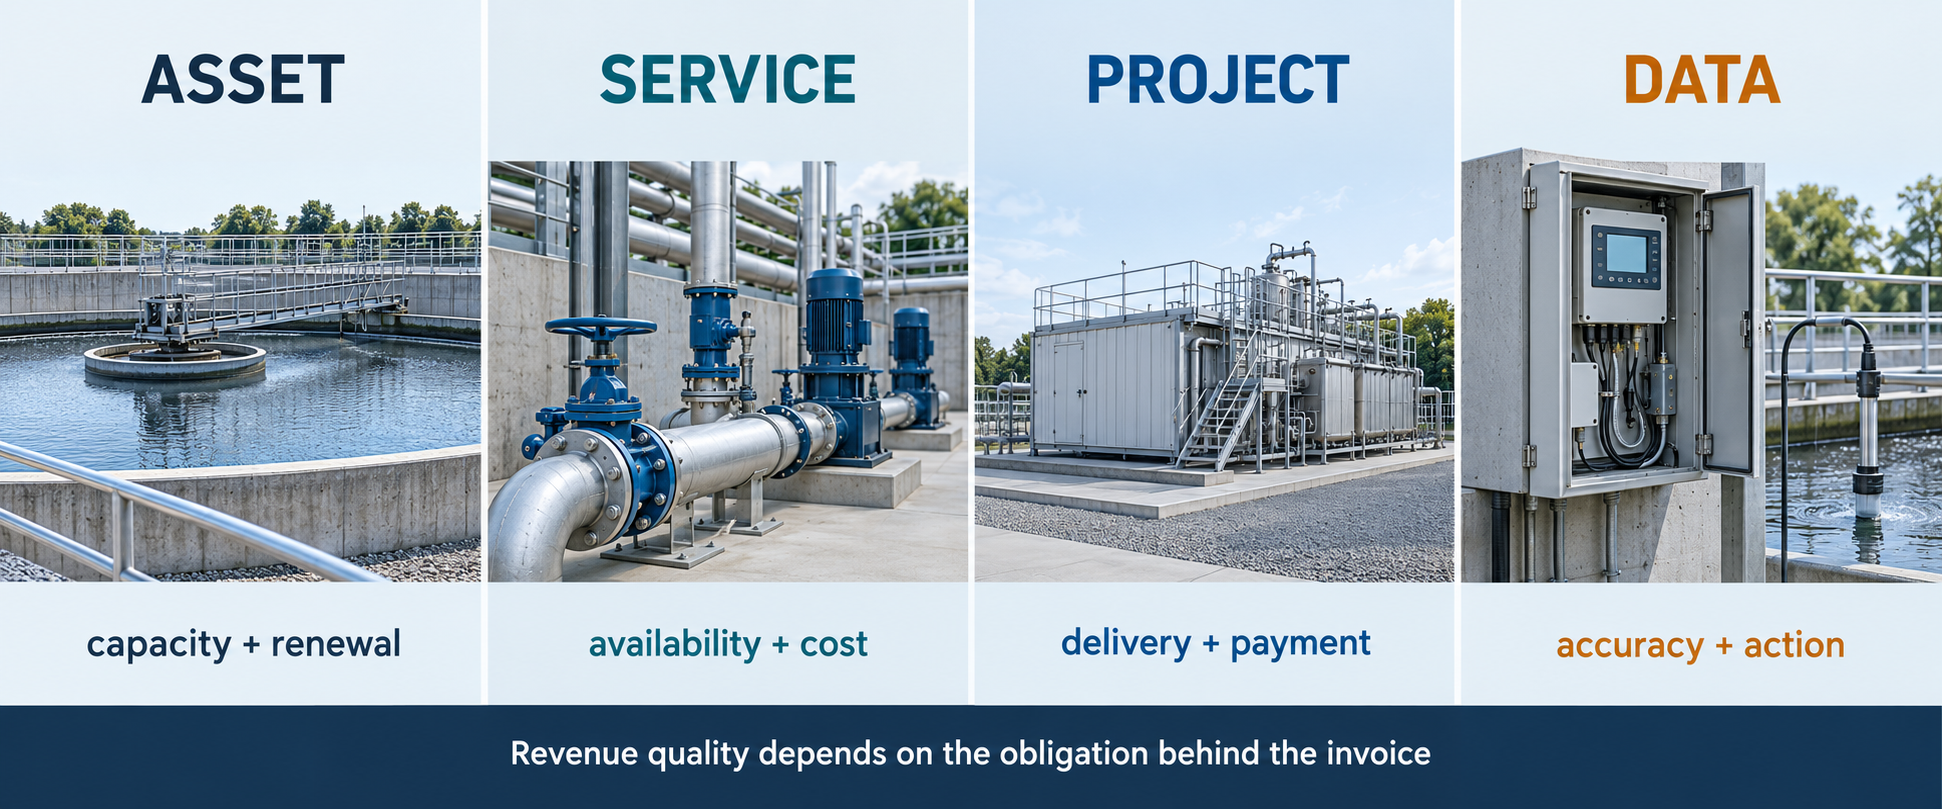
Recurring revenue is not automatically low risk. A service provider may carry labour, energy, chemical and performance obligations. An equipment business may have strong cash generation but face warranty, installation and working-capital exposure. The correct assessment connects revenue to work performed and risk accepted.
- Asset ownership: test utilisation, contract term, debt, maintenance and renewal capital.
- Operations and maintenance: test staffing, energy, chemicals, availability and service-level penalties.
- Design and delivery: test order intake, procurement, change orders, warranty and cash conversion.
- Monitoring and data: test accuracy, integration, data rights, retention and customer action.
Contracts determine revenue quality
Review the payer, term, indexation, renewal, termination, liability and performance provisions. A long contract can still be fragile if payment depends on a grant, a single offtaker or an unresolved permit. A shorter contract can be attractive when the service is essential and renewal evidence is strong.
Customer concentration also matters. One large site may provide an excellent reference, but a delay at that site can move revenue, working capital and hiring plans at the same time. Model the relationship, not only the number of customers.
Payment mechanics deserve the same attention as contract length. A project may invoice on delivery, commissioning or monthly availability, while the customer may retain part of the payment until acceptance. These terms shape funding needs and can move risk between the supplier, the owner and the financier.
Indexation also needs a clear economic link. If energy, labour or chemical costs rise faster than the contract price, a nominally recurring service can lose margin. If the contract allows repricing, test the process, timing and customer consent. A model should show both the base case and the point at which the protection no longer covers the cost base.
From project pipeline to operating cash flow
The project path has several decision gates
Wastewater projects move from a defined need through feasibility, approvals, procurement, construction, commissioning and operation. Each stage can change scope, timing, capital need and the party carrying risk. A project pipeline is therefore only as valuable as its stage, funding and conversion evidence.
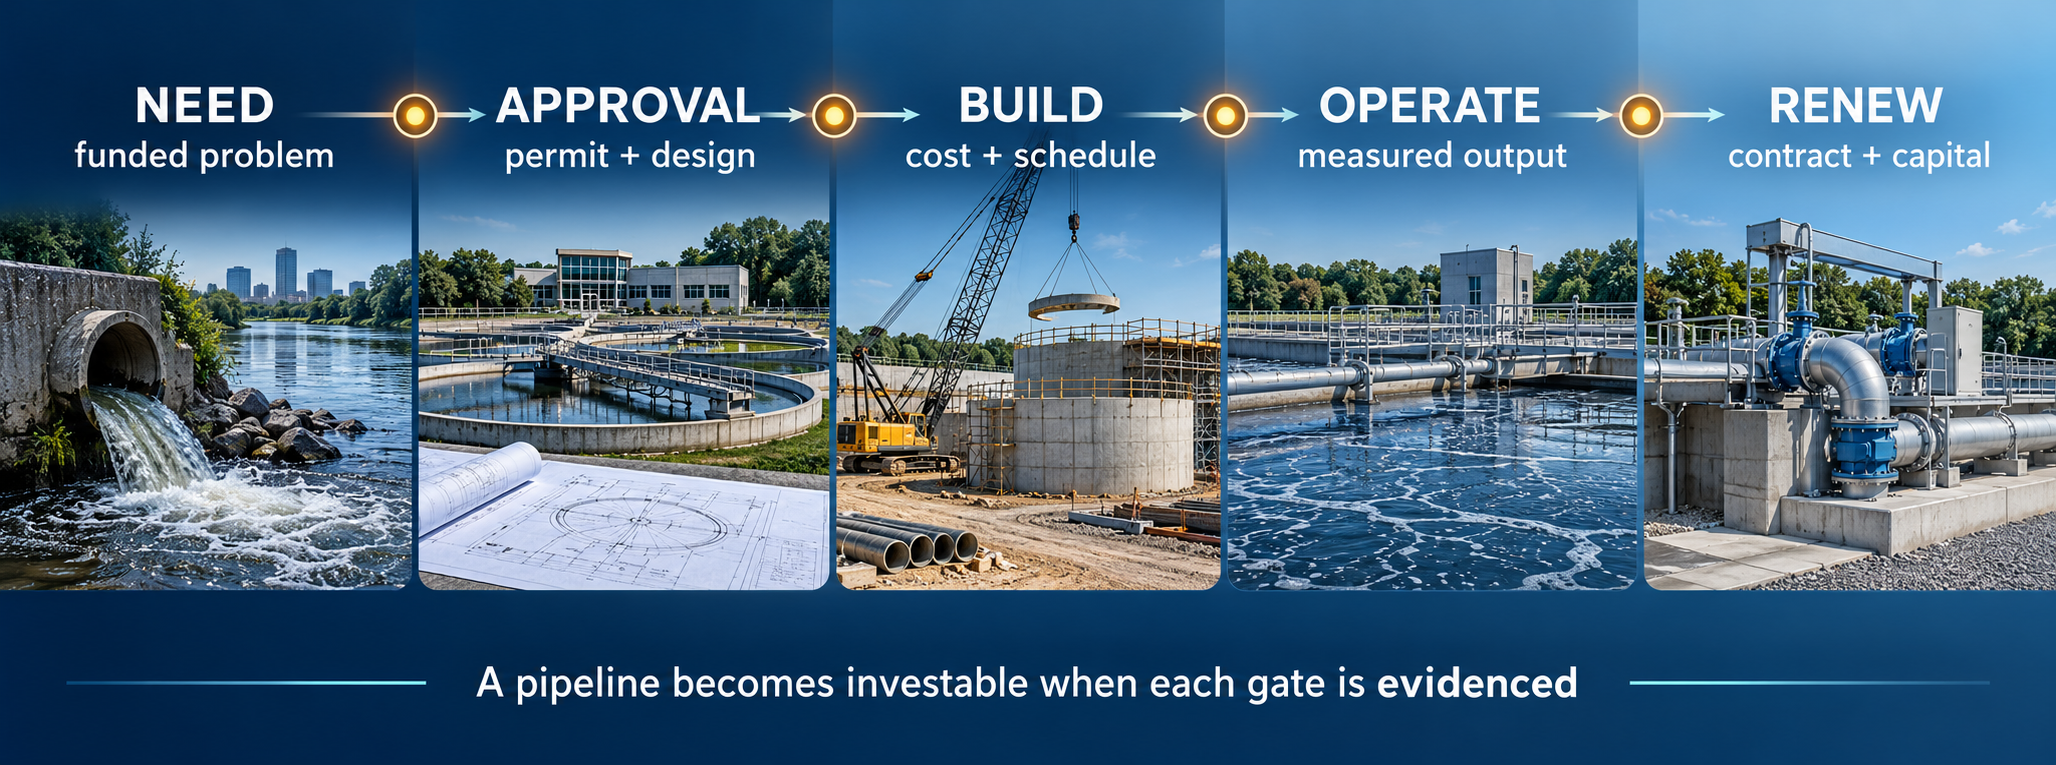
Investors should separate an early expression of interest from a budgeted project, a signed contract and an asset in operation. Check the customer decision, site control, permits, technical design, financing, procurement route and expected commissioning date. Then test what happens if any one gate slips.
Cash conversion can lag commercial traction
Infrastructure businesses can show strong demand while consuming cash. Deposits, milestone payments, retention, inventory, subcontractor terms and work in progress all affect funding needs. A model that shows revenue growth without a delivery cash profile is incomplete.
The same principle applies to reuse. A project may have a strong water-security case, but it still needs a buyer, quality specification, connection, operating plan and payment mechanism. The World Bank highlights programmatic approaches, standardised project preparation and appropriate delivery models as ways to reduce transaction costs and improve bankability.
How reuse changes the value of wastewater assets
Wastewater can become a local supply input
Reuse changes the question from “how do we dispose of used water?” to “what quality of water does this customer need, and how can it be supplied reliably?” That can create value for industrial parks, manufacturing sites, municipal users and other buyers close to the treatment asset.
Fit-for-purpose treatment means producing water to the quality required for the intended use. Higher quality can require more treatment, energy, monitoring and controls. Lower quality may be adequate for a non-potable use. The commercial case depends on the customer specification and the cost of the alternative supply.
Bankability needs more than technical feasibility
The World Bank’s Scaling ReWater work describes project preparation, transaction advice, standardised tender documents and balanced project agreements as tools to unlock private finance. These tools matter because small, bespoke projects can carry high transaction costs and unclear risk allocation.
For investors, the questions are practical. Is the offtaker creditworthy? Is quality defined and monitored? Who pays for connection and upgrades? Who carries volume, energy and compliance risk? Can the model repeat across a programme rather than relying on one exceptional site?
Where margins and scalability are won or lost
Standardisation can reduce delivery friction
Scale may come from repeatable plant modules, standard contracts, a regional service network, a software layer or a portfolio of contracted assets. Each route has its own bottleneck. Manufacturing needs quality control and inventory. Services need local talent. Digital systems need integrations and retention. Assets need capital and utilisation.
A business is not scalable merely because the market is large. Ask what must increase for revenue to grow, and whether that input can grow without the same increase in bespoke engineering, project management or working capital.
Margins need a physical explanation
In treatment operations, margins can move with electricity, chemicals, labour, sludge handling, maintenance and replacement parts. In construction, they can move with procurement, subcontractors, commissioning and variation orders. In monitoring, they can move with connectivity, installation, support and customer integration.
Technology risk can also become financial risk. A system that underperforms may require additional treatment, redesign, compensation or replacement. Review warranties, liquidated damages, insurance, acceptance tests and the evidence that supports the performance claim.
Maintenance access is another scale constraint. Assets may need planned shutdowns, specialist parts, laboratory testing or trained operators. A company that depends on one supplier or one technical founder may have a fragile delivery model even when the installed equipment is sound.
Defensibility can come from more than a patent. It may come from operating data, approvals, reference sites, integration knowledge, service coverage or a trusted position in a long procurement cycle. Investors should ask which advantage survives a customer tender and which advantage depends on one relationship.
UK, Europe and GCC: different routes to opportunity
UK and Europe
UK demand is shaped by regulated company plans, drainage and wastewater management planning, environmental requirements and public scrutiny. Europe adds the recast Urban Wastewater Treatment Directive and national implementation. These drivers can create upgrade and service demand, but the procurement route and funding decision remain local.
The EIB’s 2026 water-systems paper is useful for investors because it links infrastructure outcomes to how projects are originated, coordinated, funded and financed. A project with strong policy support still needs a credible sponsor, contract and delivery team.
GCC markets
GCC markets can present demand linked to water security, desalination, reuse, urban development and industrial expansion. The region is not one market. Diligence must cover the exact jurisdiction, offtaker, energy profile, local partner, currency, import route, contractor structure and payment protections.
Regional relevance should sharpen the questions rather than encourage a generic growth story. A technology may travel well, while an operating model, permit pathway or service network may not. Cross-border investors should assess how the business will support the asset after commissioning.
For portfolio construction, this distinction matters. An equipment supplier, an operating asset and a monitoring platform can all sit within wastewater infrastructure, but their exposure to construction, utilisation, regulation and working capital is different. A portfolio may benefit from that variety only when the risks are understood rather than grouped under one sector label.
Wastewater infrastructure diligence: five questions
Customer and contract
First, who pays and why now? Verify the budget owner, procurement route, contract term, payment protections and alternatives. A public policy need becomes an investable opportunity only when the spending route is clear.
Permit and performance
Second, what approvals and operating standards apply? Confirm permits, monitoring obligations, acceptance tests, warranties and the evidence behind performance claims. Separate a pilot result from a paid asset operating under contractual obligations.
Capital and scale
Third, what capital is required before cash arrives? Model construction, connection, commissioning, working capital, debt, maintenance and renewal. Fourth, what can repeat, and what remains bespoke? A strong pipeline can still produce weak returns if every deployment requires a new delivery model.
Impact and governance
Fifth, can the business prove environmental and operating outcomes without overclaiming? Review discharge data, reuse volumes, energy use, incidents, safety, data rights and customer reporting. Governance is part of infrastructure quality because failures can cause fines, delays, remediation costs or lost contracts.
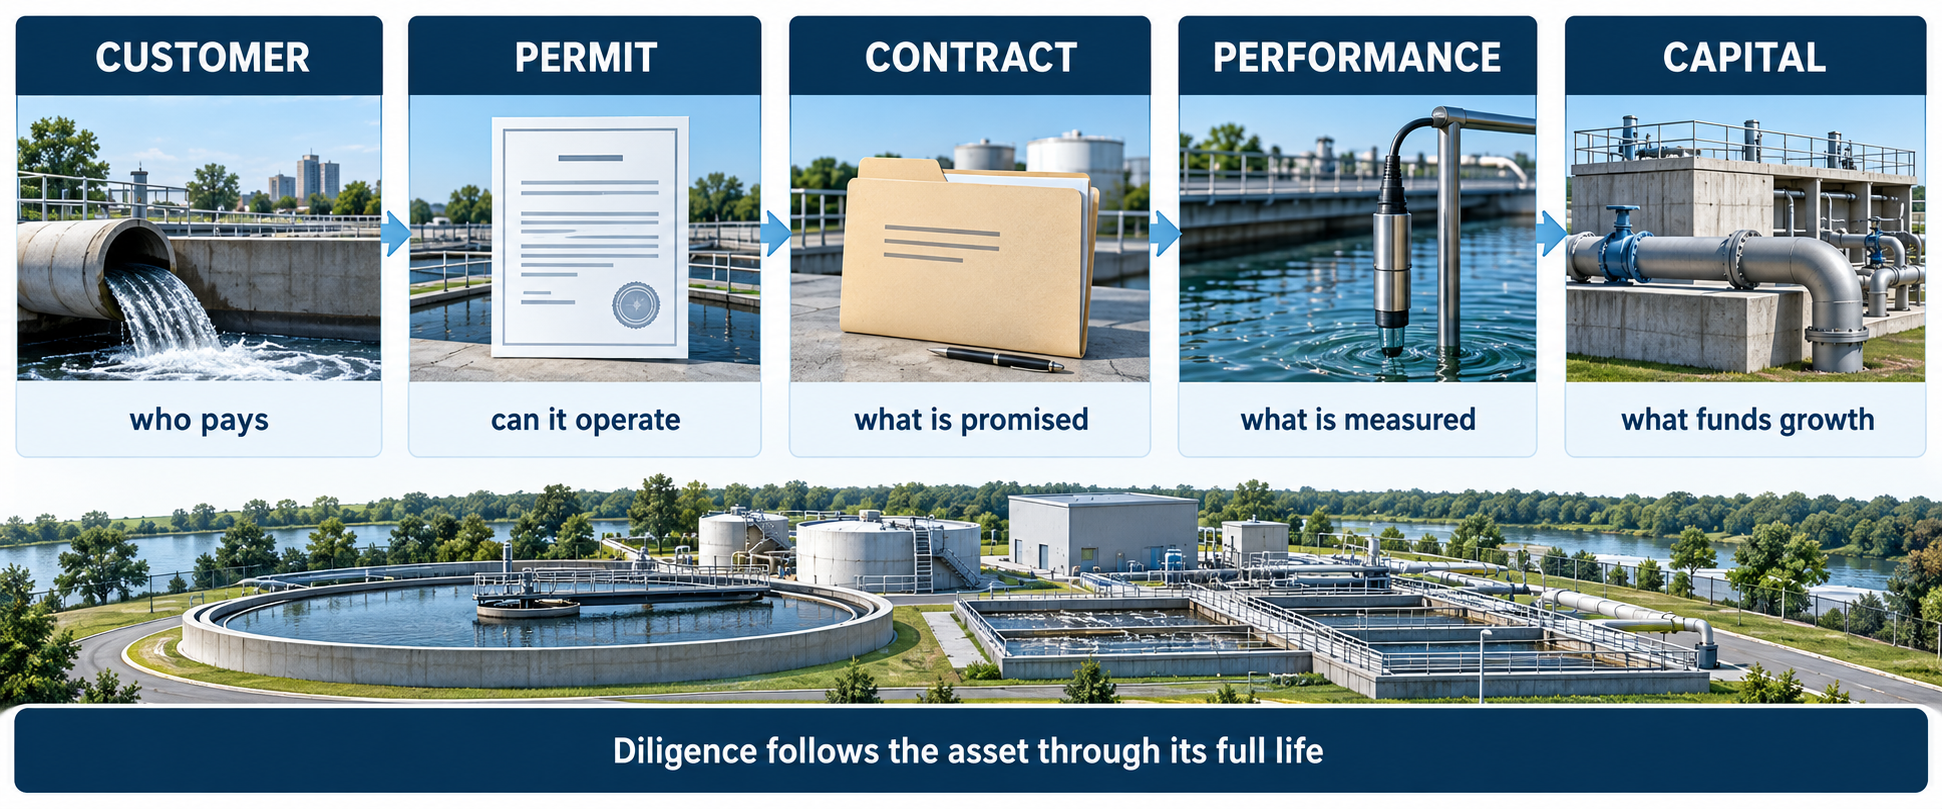
The strongest opportunities make these answers easy to verify. They show a defined asset, a credible customer, a permitted route to operation, transparent economics and a practical plan for repeat deployment.
Frequently asked questions
What is wastewater infrastructure?
Wastewater infrastructure includes the networks, treatment works, storage, monitoring, reuse systems and supporting services used to collect, treat and manage used water. The investment risk depends on the asset, contract, permit and operator.
Why can wastewater infrastructure attract private capital?
It can address funded needs linked to compliance, capacity, resilience, industrial continuity and water reuse. Private capital still requires a clear payer, delivery route, performance evidence and risk allocation.
Is wastewater infrastructure a defensive investment?
Some assets may benefit from essential demand or long contracts, but no label removes construction, regulatory, technology, energy, counterparty or renewal risk. Each opportunity requires its own diligence.
How does water reuse affect the investment case?
Reuse can turn treated wastewater into a local supply for a defined customer. The case depends on fit-for-purpose quality, an offtaker, connection costs, regulation, energy use and a bankable contract.
What should investors review first?
Start with the customer, contract, permit and operating evidence. Then test capital needs, margins, cash conversion, scalability, governance and measurable impact.
Explore direct water-technology opportunities
Wastewater infrastructure can support durable commercial activity, but the investable case is specific. It rests on a defined asset or service, a funded customer need, credible delivery evidence and economics that remain workable through operation and renewal.
Water Investment Network helps eligible investors review direct water-technology opportunities with a focus on commercial fit, evidence and execution risk. Explore the water-technology portfolio, read the water market investment thesis, or contact the network with a specific question.
If you are assessing opportunities aligned with this market, join the network to discuss the next step. This is an introduction to private opportunities, not a recommendation or regulated advice.
- European Investment Bank, Future-proofing Europe’s water systems: From vision to investment.
- World Bank, Scaling Water Reuse: A Tipping Point for Municipal and Industrial Use.
- World Bank, Water for People and Scaling ReWater.
- GOV.UK, Drainage and wastewater management plans: guiding principles for the water industry.
- European Commission, Water resilience strategy.